Table of Contents
Islamic Economics: Promoting Stability and Fairness
Suppose that there are two families in the same city, both trying to purchase a house. Both have some savings and both require a loan to pay the balance. The first one agrees to pay a fixed interest rate, no matter how much his income changes, on a conventional mortgage. The second one goes to an Islamic bank, which purchases the house and resells it to the family at an agreed price, which is to be paid in installments. The monthly payment might be comparable.
It is very different as far as the legal backings and the principles it relies on. Islamic economics is an Islamic way of economic life, basing on Quran and Sunnah. It does not turn out markets, trade or profit.
It fosters wealth creation but only on the condition of abiding by ethical rules – honesty in transactions, protection of the weak, prohibition on interest (riba), prohibition on excessive uncertainty and gambling-like contracts, and obligation to share a portion of wealth with the needy. This guide explains in layman’s terms the key ideas, demonstrates what happens when they are used in practice, contrasts them with the way they are normally used, and gives a candid opinion on the criticisms.
Key Points
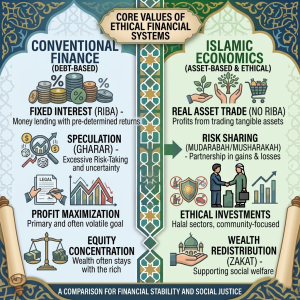
- Islamic economics combines economic activity with ethical and social goals, such as fairness, transparency and care for the poor.
- Its best-known rule is the prohibition of riba (interest). Islamic finance instead uses trade, leasing and partnership contracts.
- Risk sharing and a link to real assets are central ideas. In practice, however, many Islamic products are sale-based and look similar to conventional loans in cost.
- Zakat, charity and endowments (waqf) are the main tools for redistributing wealth.
- Islamic finance now operates in dozens of countries, and Pakistan, Malaysia, Saudi Arabia, the UAE and Bahrain are important examples.
Core Principles of Islamic Economics:
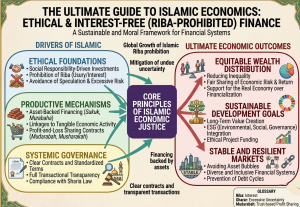
Islamic economics rests on a small set of principles that shape every financial contract and business practice:
- Fairness and justice: no party should be exploited, and the weaker side must be protected.
- Honesty and transparency: terms, prices and defects must be disclosed.
- Real economic activity: money should be linked to trade, production or genuine assets, not just to more money.
- Shared risk: those who provide capital and those who use it share the outcome in some way.
- Social responsibility: wealth carries duties to the community, through zakat and charity.
- Moral limits: some activities, such as gambling and trading in harmful goods, are outside the permitted area.
Seen together, these principles link money with ethics and aim for prosperity that reaches many people, not only the owners of capital.
Prohibition of Interest (Riba)
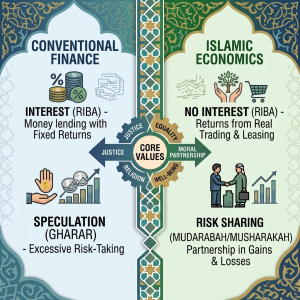
The most famous is the prohibition on riba, which is frequently interpreted as “interest” or “usury. Islamic understanding of money is not as a commodity that can be loaned and return guaranteed, it is a medium of exchange. Profit must be earned from a legitimate trade, investment and productive activity, with a certain amount of risk involved for the investor.
With a traditional loan, the lender will receive the agreed interest, regardless of the success of the business. Islamic finance, however, requires the bank to purchase an asset, lease or enter into a partnership with the other parties of the transaction and, therefore, earn a return on a real transaction.
There are details which are hotly debated among scholars as to whether all bank interest is considered as riba or only as interest from exploitative lending and this is where Islamic finance has an advisory body of Shariah boards. To read about how interest rates work in the conventional system, check out our articles on: interest rates and global economic growth.
Risk Sharing
When a bank finances a business in the name of a partnership, it shares in the profits if the business is successful and loses income if the business fails. The concept is usually stated as “no risk, no return” (NRNR): a return is to be won only by the investor’s willingness to bear a corresponding share of the risk in a business venture, rather than by the investor having it borne by the borrower. This is supposed to provide improved incentives.
If the lender is sharing the result, then he or she has a valid reason to look at the business and to select productive projects. If the borrower does not have a hardship year, then they may be better able to weather the storm of the bad year. Realistic PnL contracts are not widespread in practice.
Most Islamic banking relies on the sale and lease contracts which are not so difficult to price and critics say this is closing the gap on conventional banking. This debate will be addressed later on in the article.
Social Justice and Wealth Distribution
Islam places strong emphasis on reducing extreme gaps between rich and poor and on preventing wealth from circulating only among the rich. The main tools are obligatory and voluntary giving:
- Zakat is a compulsory yearly payment by Muslims whose wealth is above a minimum threshold (the nisab). The usual rate on savings is 2.5 percent of eligible wealth held for a lunar year. It is given to defined groups, including the poor, the needy and those in debt.
- Sadaqah is voluntary charity, which can be money, goods or help.
- Waqf is an endowment in which property or funds are dedicated permanently to a charitable purpose, such as a school, hospital or well.
- Inheritance rules divide an estate among many relatives instead of concentrating it in one person.
Here is a simple example. Suppose a person has held eligible savings of Rs 2,000,000 for a full lunar year and that amount is above the nisab. Zakat due is 2.5 percent, which is Rs 50,000. The nisab is set in terms of gold or silver and can differ by authority, so people should check the current figure with a qualified source. In Pakistan, banks generally deduct zakat at the rate of 2.5 percent from eligible savings accounts at the start of Ramadan under the Zakat and Ushr Ordinance, 1980, unless the account holder has filed a valid exemption declaration.
Ethical Business Practices
Honestly and transparency is the fundamentals of commerce. A seller is required to disclose defects in goods, and cannot defraud in weights, measures or quality. The hoarding of essential products in order to increase prices is condemned as is the practice of bribery and exploitation of workers.
The classical teaching of the Prophet (saws) on fair dealing is that a honest trader will be rewarded, while deceit brings no blessing to the trade. These rules promote trust, and trust reduces the cost of business. Markets function better where buyers and sellers are able to count on the other’s word.
Prohibition of Excessive Speculation
Islam bans two types of risky transactions. Gharar refers to over-ambiguity in a contract, e.g., to sell something that does not exist, or whose quality is not known. Maysir is gambling, which is based upon luck and a gain for one is a loss for another. In finance this restricts unnecessary speculation and promotes a principle of investing in real assets and real activities.
This decreases the danger of asset bubbles and complicated, mysterious products, supporters say. Islamic markets have their own types of risk, and not all of the Islamic products are guaranteed to be free from speculation, critics note, making supervision crucial.
How Islamic Economics Affects a Country’s Economy
Once a country implements Islamic financial principles, it impacts on banks, businesses and households. The effects are subject to the extent of application of the principles and how well they are regulated; hence the benefits outlined below are potential rather than guaranteed.
Encourages Financial Stability
Islamic finance is also able to help lower the risks that caused significant losses in conventional banking during the 2008 crisis, since it does not include speculative products, but it is rather associated with lending to real assets. But the research evidence is not conclusive.
Some studies report that Islamic banks are less vulnerable in certain periods, some others report that there is not any clear difference between the two banks or that Islamic banks have their own vulnerabilities, such as a high exposure to the property segment. A fuller discussion is in our article on the: Growth of Islamic Finance & Banking
Reduces Income Inequality
Zakat and charity transfers wealth from rich households to poor ones and the prohibition on interest is meant to prevent debt from systematically transferring wealth from borrowers to lenders. Decreased inequality can increase the spending for necessary goods and increase social cohesion.
The extent to which the zakat is collected and distributed and whether it is integrated into effective tax and welfare systems, will determine how much it will actually be able to contribute to reducing inequality.
Promotes Ethical Investment
Islamic investment rules guide money towards the productive sectors such as manufacturing, agriculture, housing, infrastructure and technology, and away from the industries deemed harmful, such as production of alcohol and gambling and certain weapons.
This is one of the aspects that dovetails into the current interest in Environmental, Social and Governance investing and some non-Muslim investors invest in Islamic funds for this reason.
Supports Small Businesses
Entrepreneurs who don’t have collateral can benefit from partnership funding. A small business that runs a business in partnership with an Islamic financial institution, instead of borrowing at a high rate of interest, shares in profits when the business expands and is not smothered by a fixed payment during a lean period.
The problem is that it’s more complicated to evaluate and follow up on such a loan, and so it is a smaller share of what banks call the sale-based product category.
Strengthens Social Welfare
Zakat, charity and waqf provide a network of support that can fund education, healthcare and relief for vulnerable families. When combined with tax revenue and public programs, they can improve access to services and financial inclusion.
Examples of Islamic Economic Practices:
Countries apply Islamic principles in very different ways. Some have a fully interest-free banking law, while others run Islamic and conventional banks side by side. The examples below show the variety.
- Malaysia runs a dual system. Its Islamic Banking Act of 1983 allowed Islamic banks to operate beside conventional ones, and it has one of the deepest Islamic capital markets and sukuk markets in the world.
- Saudi Arabia has a large banking sector in which Shariah-compliant products are widespread, and it is a major issuer of sukuk.
- The United Arab Emirates hosts Dubai Islamic Bank, widely described as the first Islamic commercial bank (1975), and Dubai and Abu Dhabi are active centers for Islamic finance and sukuk.
- Pakistan introduced a dual banking framework in the early 2000s. Meezan Bank, the first full-fledged Islamic bank, opened in 2002, and many conventional banks now run Islamic branches or windows.
- Bahrain is a regional hub for Islamic finance regulation, and it hosts AAOIFI, which issues accounting and Shariah standards for the industry.
- Iran adopted an interest-free banking law in 1983 and operates a banking system intended to be free of interest.
Global Sharia-Compliant Operational Footprint
The table summarizes the approach of each country. It is a simplified overview, and details change over time, so please check official sources for current rules.
| Country | Approach | Notable feature |
|---|---|---|
| Malaysia | Dual system (Islamic and conventional) | Deep sukuk market and a strong regulatory framework |
| Saudi Arabia | Conventional and Islamic banks with widespread Shariah-compliant products | Major sukuk issuer and one of the largest Islamic finance markets |
| United Arab Emirates | Dual system with a strong financial center | First Islamic commercial bank (Dubai Islamic Bank, 1975) and active sukuk issuance |
| Pakistan | Dual system since the early 2000s | Islamic banking has grown to roughly a fifth of banking sector assets, according to State Bank data, and the country issues sovereign sukuk |
| Bahrain | Regional regulatory and standard-setting hub | Home of AAOIFI, a standard-setting body for the industry |
| Iran | Interest-free banking law since 1983 | A banking system intended to be free of interest, counted separately in industry statistics |
Main Islamic Finance Contracts at a Glance
Islamic finance replaces interest-based lending with a handful of contract types. Knowing them makes it much easier to understand how an Islamic bank earns money and why the legal structure matters.
| Contract | How it works | Simple example |
|---|---|---|
| Murabaha (cost-plus sale) | The bank buys an asset and sells it to the customer at cost plus a disclosed profit, paid in installments | A bank buys a car for Rs 3 million and sells it for Rs 3.45 million in installments |
| Ijara (leasing) | The bank owns the asset and leases it to the customer for rent, sometimes ending in ownership transfer | A factory leases machinery from the bank for five years |
| Musharaka (partnership) | The bank and the customer both put in capital and share profit by agreed ratios and loss by capital shares | A bank and an entrepreneur jointly finance a new workshop |
| Mudaraba (profit-sharing) | One party provides capital, the other provides work and management. Profit is shared by agreed ratio, and the investor bears financial loss unless there is negligence | Depositors’ funds managed by the bank for a share of profit |
| Sukuk (asset-backed certificates) | Investors own a share in an asset or project and receive returns from its income | A government raises money through ijara sukuk backed by state assets |
| Takaful (mutual insurance) | Participants contribute to a pool that pays members who suffer a defined loss | A group of drivers share the cost of vehicle accidents |
To learn more about sukuk in particular, read our guide to Islamic sukuk.
Conventional vs. Islamic Economics
The table compares the two approaches in simplified form. In practice, the line is not always sharp. Conventional finance also has ethical funds and consumer protection, and some Islamic products behave very much like conventional ones.
| Feature | Conventional approach | Islamic approach |
|---|---|---|
| Main focus | Efficiency and profit maximization within legal rules | Economic growth together with social justice and ethical limits |
| Return on capital | Interest on loans | Profit from trade, leasing or partnership, and no interest (riba) |
| Risk | Borrower bears the main burden, and the lender’s return is fixed | Risk linked to ownership or shared between parties |
| Speculation | Permitted, including many derivatives | Excessive uncertainty (gharar) and gambling (maysir) prohibited |
| Asset backing | Not required for lending | Financing tied to a real asset or transaction |
| Redistribution | Mainly through taxes and public spending | Zakat, charity and waqf, alongside the state’s taxes |
| Screening of activities | Mostly legal screening | Excludes sectors such as alcohol, gambling and pork products |
Expanding Global Influence of Islamic Finance
Islamic finance has grown from small experiments in the 1960s into an industry with assets measured in trillions of dollars, according to industry estimates. It operates in dozens of countries and is also present in non-Muslim countries. The United Kingdom issued the first sovereign sukuk by a Western government in 2014, and financial centers such as Luxembourg and Hong Kong host Islamic products. The detailed numbers, the regions where it is growing fastest and the questions about its stability are discussed in our guide to the: growth of Islamic banking.
Challenges of Islamic Economics
Islamic economics also faces real challenges, and an honest account must include them:
- Complexity: Islamic contracts often involve extra steps, such as buying and holding an asset, which can raise costs and make regulation harder.
- Form versus substance: critics argue that some Islamic products, especially fixed-markup sales, work almost like interest-based loans. Supporters answer that the legal and risk structure is truly different.
- Different rulings: scholars in different countries sometimes disagree about what is permissible, which complicates cross-border business.
- Skills shortage: there are not enough professionals who understand both Islamic jurisprudence and modern finance.
- Public understanding: many customers do not clearly know how Islamic products differ from conventional ones, which opens the door to confusion and misleading marketing.
- Limited tools: markets for managing short-term liquidity and risk are less developed than conventional ones.
These problems do not make the framework less important, but they show why careful regulation, clear disclosure and independent Shariah governance matter. The relationship with interest-rate policy is also complex, since conventional benchmarks still influence pricing, as we explain in our article on monetary policy.
Islamic Economics: A Comprehensive Socio-Economic Model
Islamic economics is more than a set of banking rules for Muslims. It is a broad ethical framework for how people earn, spend, save and share. Its core claim is that economic life should serve human well-being and not only produce profit, and that justice, honesty and responsibility are part of economics, not separate from it.
Three features stand out. First, the ban on interest and the requirement for real assets link finance to the real economy. Second, the duty of zakat and charity builds redistribution into economic life, and gives believers a personal responsibility toward the community. Third, the moral limits on gambling, deception and harmful goods mean that profit is not the only test of a good business.
Whether this model produces better outcomes than the conventional one is an open question, and economists and scholars disagree. The evidence suggests that the model can offer real benefits, such as inclusion for people who avoid interest, and a closer link between finance and production. It also shows that results depend heavily on the quality of institutions, regulation and honest practice, in the same way as in any financial system.
In my view, the most useful way to study Islamic economics is neither to treat it as a perfect alternative nor to dismiss it, but to ask specific questions: what does a particular product do, who bears the risk, what does it cost, and who supervises it? That approach respects both the values behind the system and the need for evidence. This is my own interpretation, offered as a way of thinking.
Summary
Islamic economics combines economic activity with moral and social goals. Its key ideas are the ban on interest, risk sharing, a link between finance and real assets, ethical business conduct and redistribution through zakat and charity. These ideas are put into practice in countries such as Malaysia, Saudi Arabia, the UAE, Pakistan, Bahrain and Iran, in different ways and with different results.
The framework brings real strengths, including inclusion, ethical screening and a stress on real economic activity. It also faces real challenges, including complexity, disagreement among scholars, a shortage of skills and the question of how different some products are from conventional loans. Readers who want to explore further can follow the links in this article to our guides on sukuk, Islamic banking and monetary policy.
Frequently Asked Questions
What is Islamic economics in simple words?
It is an approach to economic life based on Islamic teachings. It allows trade and profit but bans interest, requires honesty, limits gambling-like contracts and obliges wealthier people to share some of their wealth.
Why is interest (riba) prohibited in Islam?
Islamic teaching holds that earning a guaranteed return on money alone, without sharing any risk or producing anything, is unfair, especially to borrowers in need. Returns should come from trade, investment and real economic activity.
How do Islamic banks make money without interest?
They earn profit from selling assets at a markup (murabaha), renting assets (ijara), sharing profits in partnerships (musharaka and mudaraba) and from fees for services.
Is Islamic finance the same as conventional finance with a different name?
Not exactly. The legal structure is different, because the bank must own an asset or share real risk. However, critics argue that some products have a similar cost and effect, so customers should compare terms carefully.
What is zakat and how much is it?
Zakat is a yearly obligatory payment on wealth above a threshold (the nisab). The usual rate on savings held for a full lunar year is 2.5 percent.
Can non-Muslims use Islamic finance?
Yes. Islamic banks and funds serve customers of all backgrounds, and many non-Muslim investors use sukuk and Islamic funds.
Is Islamic finance safer?
It can reduce some risks, such as exposure to speculative products, but it has its own risks. Research findings are mixed, and the quality of regulation and management matters in both systems.
Editorial Note
This article was written by Siraj Buzdar for Tech and Tips Economy as a general educational introduction to Islamic economics. It explains economic concepts and does not give religious rulings. Questions about what is permissible should be put to qualified scholars. Descriptions of countries and institutions are simplified and based on publicly available sources, including the standard-setting bodies and central banks listed below. The zakat example uses invented numbers for illustration, and the nisab and the rules for zakat deduction should be checked with an authoritative source.
The paragraph that begins “In my view” is the author’s own interpretation. This content is for general education only and is not financial, investment, legal or religious advice. This article was last reviewed in November 2026. If you notice an error, please tell us through our contact page.
Reference
- The Potential Growth and Future Trends of Green Sukuk as a Tool for Sustainable Financing
- Islamic Financial Services Board (IFSB)
- Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI)
- State Bank of Pakistan: Islamic Banking Bulletin

As an economics writer at Tech and Tips Economy, Siraj Buzdar focuses on demystifying economic policies and financial data. His primary goal is to ensure that general economic topics are clear and easy to understand for the everyday reader. By adjusting the depth and length of his articles based on topic complexity, Siraj works tirelessly to bring approachable economic insights directly to his audience.