Table of Contents
Brief About the Israel-Iran Conflict vs. COVID-19: Global Economic Impact
Every few years, something arrives that economic models did not see coming. In 2020, it was a virus. In 2026, it is a war in the Gulf. The two shocks could hardly be more different, yet people keep comparing them, and for good reason: both pushed up living costs, both rattled investors, and both showed how tightly the world economy is wired together.
This article puts them side by side. It looks at what COVID-19 did to the global economy, what the war involving Israel, Iran and the United States has done so far, and which of the two has hurt more. Wherever a number appears, the institution behind it is named so that you can check it yourself. The figures describe the situation as of late September and mid-October 2026, and they may have changed since then.
Key Takeaways
- COVID-19 is still the bigger shock. It pushed almost every economy into contraction in 2020, and in 2022 the IMF projected that the cumulative loss of output through 2024 would exceed $12.5 trillion.
- The war is not a small regional story. The World Bank expects global growth of just 2.5% in 2026, the weakest since the pandemic, largely because of the war and the disruption around the Strait of Hormuz. The IMF’s October outlook is higher at 3.1%, and a later section explains why the two numbers differ.
- The damage travels through different channels. COVID-19 hit people’s movement and work. The war hits energy, shipping and fertilizer, and then spreads into prices.
- Energy-importing countries such as Pakistan feel it through fuel bills and, eventually, through the cost of almost everything else.
COVID-19: The Shock That Shut Economies Down
The pandemic turned a health emergency into an economic one within weeks. Governments closed borders, factories and shops to slow the virus, and demand fell off a cliff. Global output shrank by roughly 3% in 2020, and international trade dropped sharply as ports, airlines and supply chains seized up.
What the Pandemic Did to the Economy
Job losses spread across the world, and tourism came close to a standstill. Manufacturing slowed, and consumer spending sank while lockdowns lasted. Small businesses took the hardest knock because they had little cash to survive long closures. Governments spent heavily on healthcare and emergency support, which pushed public debt higher in many countries.
There was also a lasting change in habits. Remote work, online shopping and the digital economy grew far faster than they otherwise would have, because people had no other choice.
Oil deserves a special mention. Because so little travel was happening, demand collapsed and prices crashed. In April 2020, the main US crude benchmark briefly traded below zero. That is the opposite of what we see in the current war, and it matters when comparing the two crises.
Countries Hit Hardest
No two economies suffered in the same way. The differences came down to how each country earned its living and how long its restrictions lasted.
- Italy and Spain: Early outbreaks strained hospitals, and tourism, which both countries depend on, dried up.
- United States: Unemployment jumped in the first months of the pandemic. Airlines, hotels and retailers lost the most.
- China: Factory and transport restrictions early in 2020 disrupted production that the rest of the world relies on.
- India: Long lockdowns hit the informal workforce especially hard, and many small firms struggled to survive.
Industries Hit Hardest
Travel and tourism were the first casualties. With borders closed, hotels and airports emptied, and restaurants lost customers overnight. Factories stopped for lack of workers and materials, while retailers saw physical sales drop as people stayed home. Concerts, sports and other public events were cancelled or postponed almost everywhere.
- Tourism and hospitality
- Aviation
- Manufacturing
- Retail
- Transport
- Entertainment and events
The Israel–Iran War: A Shock That Runs Through Energy
The current crisis began on February 28, 2026, when the United States and Israel launched strikes on Iran. Iran responded by choking off shipping through the Strait of Hormuz, the narrow waterway that normally carries about one-fifth of the world’s oil. The International Energy Agency has described the resulting disruption as the largest in the history of global energy supply. A ceasefire reached in the spring has proved fragile, and as of late September, fighting and attacks on shipping continued while negotiations remained stuck.
The Crisis Timeline at a Glance
The war has moved in phases, and each phase has left its mark on energy prices and growth forecasts. The table below lists the main turning points that this article relies on.
| When | What happened | Why it matters economically |
|---|---|---|
| February 28 | The United States and Israel launched strikes on Iran, and Iran restricted shipping through the Strait of Hormuz | Roughly one-fifth of the world’s oil trade was suddenly at risk |
| March | Brent crude climbed to roughly $120 a barrel | Fuel and freight costs rose around the world |
| Spring | A ceasefire was agreed but proved fragile | Prices eased, yet traffic through the strait never returned to normal |
| June | The World Bank cut its 2026 global growth forecast to 2.5% | Weakest expected growth since the pandemic |
| Late September | Brent traded around $103, and only about ten commodity vessels crossed the strait on a single day | Energy costs stayed high and shipping stayed disrupted |
| October 13 | The IMF projected 3.1% global growth and assumed the strait would reopen from March 2027 | Growth held up better than feared, but inflation was forecast to rise to 4.7% |
Oil Prices and the Strait of Hormuz
Oil is where war reaches everyone. Brent crude climbed to roughly $120 a barrel in March, eased when the ceasefire raised hopes of a deal, and was back above $100 for much of the autumn. In mid-September it briefly touched about $108, and in late September it was trading around $103. The World Bank’s baseline assumes that Brent will average $94 in 2026, which is 36% higher than last year, while the IMF’s October outlook assumes an average of about $96.
Shipping through the strait has not recovered. Reuters-compiled data showed only about ten commodity vessels crossing on a single day in late September, a small fraction of normal traffic. Shipowners are wary because tankers have been attacked, and insurance and freight costs have risen with the risk.
Higher oil prices raise the cost of moving goods, running factories and generating electricity. Countries that import most of their energy also see pressure on their trade balances and foreign-exchange reserves. Over time, those costs feed into general inflation. The World Bank expects global inflation to reach about 4% this year, up from 3.3% in 2025, and the IMF’s October forecast is higher still at 4.7%. The consequences can be summarized in four points:
- Higher transport and shipping costs
- More volatile financial markets
- Weaker investor confidence
- Bigger defense budgets in the countries involved
The Economic Cost of the War for the Main Players
Beyond the military toll, the war has cost the countries involved in production, trade, energy revenue and public finances. Each has been hit in a different way, depending on how directly it is involved.
| Country | Measurable economic cost or impact | Main economic pressure |
|---|---|---|
| Iran | GDP fell 10.1% year on year in the first quarter of the Iranian calendar year 2026, and its oil and gas sector contracted by 26% | Oil exports, foreign-exchange earnings, industrial production, trade and domestic economic activity |
| Israel | The 2026 GDP growth forecast was reduced from 4.8% to 3.5%, a downward revision of 1.3 percentage points after the war-related shock | Defense spending, labor shortages, energy costs, supply constraints, tourism and investment |
| United States | Military operations against Iran had cost approximately $38 billion by August 1, 2026, according to the CBO, and a later US Central Command estimate put the cost at $43.6 billion by September 3 | Military expenditure, ammunition replacement, energy prices, inflation and federal finances |
| Middle East and Central Asia (region) | The IMF expects the region to contract by 0.3% in 2026 | Disrupted oil output and exports, damaged infrastructure and weaker investment |
Who Else Feels It
You do not have to be a party to the war to pay for it. Countries that buy most of their energy abroad are the most exposed, and the pain is worse where budgets and currencies were already fragile. The IMF notes that prices of refined petroleum products have stayed far above their pre-war levels, which squeezes economies that depend on imported fuel.
- Gulf producers face nearly zero growth this year, according to the World Bank, because their own exports are stuck behind the disrupted strait.
- Germany relies heavily on imported energy, so its industry is sensitive to every jump in oil and gas prices.
- Japan imports most of its energy and is exposed to swings in the global oil market.
- Pakistan may see higher import bills, more inflation and pressure on foreign-exchange reserves when oil stays expensive.
Industries Most Exposed
The effects go well beyond the battlefield. Energy is the obvious casualty, but anything that depends on stable trade routes and predictable fuel costs is affected. Farmers face higher fuel and fertilizer costs, which the World Bank expects to feed into food prices. Factories and construction firms slow down when materials and energy get more expensive.
- Oil and gas
- Shipping and distribution
- Aviation and tourism
- Agriculture and fertilizer
- Financial markets
- International trade
Countries Most Affected
The heaviest burden falls on the countries closest to the fighting and on the Gulf economies whose exports must pass through the strait. Damage to infrastructure and energy facilities, interrupted production and weaker investment have hit them first, while neighboring economies have also suffered from higher security costs and lost trade.
- Iran: The economy was already under strain from sanctions and limited access to investment, and the war has deepened the contraction in output and oil exports.
- Israel: Defense spending, labor shortages and a drop in tourism have weighed on growth, and the 2026 forecast was cut.
- Gulf economies: The IMF sharply downgraded its forecasts for Gulf countries, and reported figures show industrial output in Saudi Arabia falling sharply because of disrupted oil production.
- The wider Middle East: Rising energy prices, hindered trade and weaker investment have spread economic insecurity across the region.
Industries Hardest Hit by the Conflict:
The conflict hurts not only on the battlefield but also in industries that rely on consumer confidence, working infrastructure and a stable trading environment. When production, transport or supply facilities are threatened, fuel and energy markets are disrupted first. Farm productivity then suffers because inputs become scarcer and more costly, and goods find it harder to reach markets. Manufacturing and construction slow down when factories, supply networks or infrastructure are damaged or when conditions become too uncertain to plan.
- Oil and gas: output, exports and prices swing with every headline
- Shipping and distribution: higher insurance and freight costs
- Aviation and services: costlier jet fuel and weaker travel demand
- Manufacturing and financial markets: higher input costs and nervous investors
- International Trade
COVID-19 vs the Israel–Iran War: Side by Side
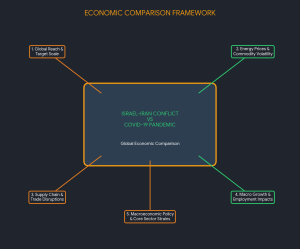
The two crises are different in kind. COVID-19 limited economic activity through lockdowns, health precautions and labor shortages. The war works through geopolitics, energy markets, shipping routes and investor nerves. The pandemic touched nearly every sector at once, while the war’s effects are sharpest in energy, transport and trade, and then spread outward through prices.
| Factor | COVID-19 pandemic | Israel–Iran war |
|---|---|---|
| Cause | Global health emergency and lockdowns | Military conflict and disruption of the Strait of Hormuz |
| Global reach | Almost every economy at once | Global through energy and prices; hardest for the Gulf and energy importers |
| Employment | Severe job and income losses worldwide | Heaviest in war-affected countries; indirect elsewhere through higher costs |
| Trade | Sharp fall in world trade in 2020 | Severe in energy and shipping; higher fertilizer and freight costs |
| Supply chains | Widespread factory, port and transport disruption | Concentrated in energy, shipping and fertilizer |
| Energy prices | Collapsed as demand dried up | Sharply higher, with Brent above $100 for much of the period |
| Effect on world growth | Global output fell by roughly 3% in 2020 | World Bank cut 2026 global growth to 2.5%, the lowest since the pandemic; the IMF projects 3.1% |
| Status | Emergency is over; costs are still being counted | Ongoing, with an uncertain outcome |
Which Crisis Hit the Global Economy Harder?
On the evidence so far, COVID-19 was the larger shock. It caused a global contraction, shut down whole sectors at once and forced governments into emergency spending on a scale rarely seen in peacetime. By contrast, the world economy is still growing in 2026, even if slowly: the World Bank forecasts 2.5% and the IMF 3.1%.
That is not the same as saying the war has been minor. The World Bank cut its forecasts for two-thirds of countries because of it, and it warns that growth could fall to 1.3% if energy disruptions worsen and financial stress builds. The IMF’s more optimistic figure partly reflects a strong technology and AI investment cycle that offsets some of the war’s drag, so the outcome varies a lot by country. The IMF describes the result as a split outlook, in which energy-importing countries outside the technology boom are the most vulnerable.
There is one more difference that is easy to miss. COVID-19 is now a finished chapter with a final bill. The war is not. Its economic cost depends on whether the Strait of Hormuz reopens, whether the ceasefire holds, and how long oil stays above $100. If the disruption drags on, the gap between the two crises could narrow.
Why the IMF and the World Bank Give Different Growth Numbers
Readers often notice that the two institutions publish different headline figures for the same year. The gap is partly about timing and partly about method. The World Bank’s 2.5% comes from its June forecast and weights countries by market exchange rates. The IMF’s 3.1% comes from its October outlook, and its main measure weights countries by purchasing power. Summaries of the IMF report note that its own tables show about 2.5% when countries are weighted by market exchange rates, so the two views are closer than the headlines suggest.
| Item | World Bank (June 2026) | IMF (October 2026) |
|---|---|---|
| Global growth, 2026 | 2.5% | 3.1% |
| Global inflation, 2026 | About 4% | 4.7% |
| Oil price assumption | Brent averaging $94 | Oil averaging about $96 |
| Severe scenario | Growth could fall to 1.3% | Oil near $130 and higher long-term interest rates |
| Strait of Hormuz | Disruption assumed to ease gradually | Reopening assumed from March 2027 |
Economic Analysis of the Two Crises
The COVID-19 pandemic and the Iran–Israel war hurt economies through different channels, but both put real pressure on households, businesses, governments and national budgets. This section looks at each crisis on its own terms, uses Pakistan as a practical example, and then asks what the two have in common.
How COVID-19 Damaged Economies
During the pandemic, lockdowns, movement restrictions, broken supply chains and weak consumer spending slowed growth and pushed prices up in many countries. Pakistan was among the countries that chose targeted “smart” lockdowns instead of keeping the whole country shut for long stretches. The World Bank has noted that these micro-lockdowns, together with cash transfers and support for businesses, helped activity recover after the contraction recorded in fiscal year 2020.
The pandemic also showed how quickly a health crisis can become an economic one. Manufacturing, tourism, transport, retail and small businesses all faced severe disruption, while governments had to spend more on healthcare, social protection and emergency support. Pakistan’s economy contracted in FY2020 and then recovered as restrictions eased. Inflation stayed a concern throughout, mainly because rising food prices weighed most heavily on lower-income families.
How the Israel–Iran War Damages Economies
The war has followed a different path. Damage to infrastructure and energy facilities, interrupted production, uncertainty over regional trade and pressure on oil markets have created risks well beyond the countries that are fighting. The situation became far more serious once shipping through the Strait of Hormuz was severely disrupted. Reuters-compiled shipping data show traffic through the strait still far below normal, with only around ten commodity vessels crossing on a single day in late September. That underlines how much global energy and commodity trade depends on this one route.
Because energy markets and international shipping are so closely linked, the shock has spread well beyond the region. Higher oil prices raise transport and production costs, inflate import bills for energy-dependent countries and push up consumer prices. Brent crude traded above $100 a barrel for much of the past few months, including about $103 in late September, while the conflict and the negotiations remained unresolved.
Pakistan: A Country Affected Without Fighting
Pakistan shows how a regional war can hurt an economy that is not part of the fighting. Higher international energy prices raise the local cost of petrol and diesel, and that puts pressure on transport, electricity, production and household budgets. Economists call the next step a second-round effect: once energy gets more expensive, the higher cost gradually shows up in the prices of many other goods and services.
The latest official numbers fit that pattern. According to the Pakistan Bureau of Statistics, headline inflation was 10.26% in September 2026, up from 5.76% a year earlier, and the State Bank of Pakistan kept its policy rate unchanged at 11.5% in September. Higher energy and transport costs were among the main drivers.
Pakistan at a Glance: Key Indicators
| Indicator | Latest figure | Source |
|---|---|---|
| Headline inflation (CPI) | 10.26% in September 2026, compared with 5.76% in September 2025 | Pakistan Bureau of Statistics |
| Policy rate | 11.5%, kept unchanged on 14 September 2026 | State Bank of Pakistan |
| Real GDP growth, FY 2025-26 | 3.7% | Pakistan Economic Survey 2025-26 |
| Main exposure | Imported oil and gas, which feed into transport, electricity and food costs | Energy-import dependence |
Comparing the Two Crises
The comparison points to one clear difference. COVID-19 restricted economic activity mainly through health measures, lockdowns, labor disruption and reduced mobility. The Iran–Israel war passes its effects on through destruction, energy markets, shipping routes, geopolitical uncertainty and military spending. In both cases, though, ordinary households end up paying: their purchasing power weakens, living costs rise, jobs become less secure, and the future feels less certain.
The Broader Lesson
Economic stability can be shaken by events that start far outside the economy. A pandemic interrupts production by restricting how people move. A conflict creates similar pressure by disrupting energy supplies, trade routes, infrastructure and investor confidence. The continuing disruption around the Strait of Hormuz is a clear example of how a regional conflict can grow into a global economic concern when a strategically vital shipping route is affected.
Conclusion
COVID-19 remains the biggest economic shock of this century so far. It was global, immediate and deep, and its effects are still visible in debt levels, supply chains and the way we work. The Israel–Iran war is smaller in overall scale, but it is far from minor. It has disrupted the world’s most important oil route, pushed prices above $100 and dragged global growth to its weakest level since the pandemic.
The bigger lesson is that economies can be shaken from outside the economy: by a virus one year, by a naval blockade the next. Readers who want to stay ahead of the next shock should watch three things: oil prices, shipping through key chokepoints, and how their own country pays for its energy.
Frequently Asked Questions
Figures in this section reflect the situation described in this article in late September and mid-October 2026. Events are moving quickly, so check the sources in the reference list for updates.
When did the current conflict begin, and who is involved?
The crisis started on 28 February 2026, when the United States and Israel launched strikes on Iran. Iran answered by choking shipping through the Strait of Hormuz. A ceasefire reached in the spring has proved fragile, and by late September, attacks on shipping and stalled negotiations were still part of the picture.
Why does the Strait of Hormuz matter so much for the world economy?
It is a narrow waterway that normally carries about one-fifth of the world’s oil. Because few alternative routes exist, any serious interruption pushes up prices everywhere, not just near the Gulf. The International Energy Agency has described the current disruption as the largest in the history of global energy supply.
How high have oil prices gone?
Brent crude climbed to roughly 120 dollars a barrel in March, eased when the ceasefire raised hopes of a deal, and spent much of the autumn above 100 dollars. It was trading around 103 dollars in late September. The World Bank’s baseline assumes an average of 94 dollars for 2026, about 36 percent higher than last year, and the IMF assumes about 96 dollars.
Which hurt the global economy more, COVID-19 or this war?
On the evidence so far, COVID-19 was the bigger shock. Global output shrank by roughly 3 percent in 2020, and in 2022 the IMF projected a cumulative output loss of more than 12.5 trillion dollars through 2024. The world economy is still growing in 2026, although slowly. That said, the war is not minor, and its final cost depends on whether the strait reopens and how long oil stays expensive.
Why do the World Bank and the IMF give different growth forecasts?
The World Bank expects global growth of 2.5 percent in 2026, while the IMF’s October outlook projects 3.1 percent. The two institutions published at different times and weight countries differently: the World Bank uses market exchange rates, and the IMF’s main measure uses purchasing power. Summaries of the IMF report say its own figure is about 2.5 percent on the market-rate basis, so the difference is smaller than it looks.
How can Pakistan be affected if it is not part of the fighting?
Pakistan buys much of its energy from abroad, so expensive oil raises the cost of petrol and diesel almost immediately. That pushes up transport and electricity costs, squeezes household budgets and puts pressure on foreign-exchange reserves. Economists call the later stage a second-round effect: once energy gets costlier, the higher cost gradually shows up in food and other goods.
Will petrol and electricity prices in Pakistan keep rising?
Nobody can promise either way. Local fuel prices depend on three main things: the global oil price, the rupee’s exchange rate against the dollar, and government taxes or levies. If oil stays above 100 dollars and the rupee weakens, pressure continues. If shipping through the strait normalizes, some of that pressure could ease. Following all three together gives a better picture than watching oil alone.
Is this war causing inflation around the world?
It is adding to it. The World Bank expects global inflation of about 4 percent this year, up from 3.3 percent in 2025, and the IMF’s October outlook puts it at 4.7 percent. Higher fuel, freight and fertilizer costs raise prices for transport, manufacturing and food, and the effect is strongest in countries that import most of their energy.
How much has the war cost the countries directly involved?
The article cites several estimates. Iran’s economy shrank by 10.1 percent year on year in the first quarter of its calendar year, with the oil and gas sector contracting by 26 percent. Israel’s 2026 growth forecast was cut from 4.8 percent to 3.5 percent. The US Congressional Budget Office put American military costs at about 38 billion dollars by 1 August, and a later US Central Command estimate reached 43.6 billion dollars by 3 September.
Why did oil prices collapse during COVID-19 but surge now?
The two shocks hit opposite sides of the market. During the pandemic, lockdowns wiped out travel and factory demand, so too much oil chased too few buyers, and in April 2020 the main US benchmark briefly traded below zero. Today, the problem is supply: a key shipping route is disrupted, so buyers compete for fewer barrels that can reach them safely.
Which industries are most exposed to the war?
Energy and shipping feel it first, followed by aviation and tourism, which depend on fuel and stable routes. Agriculture is also vulnerable because farmers face higher fuel and fertilizer costs, which the World Bank expects to feed into food prices. Manufacturers and construction firms slow down when materials and power get more expensive.
Could the economic damage get worse?
Yes. The World Bank warns that global growth could fall to 1.3 percent if energy disruptions worsen and financial stress builds, and the IMF’s own severe scenario has oil near 130 dollars. The outcome hinges on whether the Strait of Hormuz reopens fully, whether the ceasefire holds and how long oil stays above 100 dollars.
What should ordinary readers and small businesses watch?
Three signals are enough for most people: the oil price, the amount of traffic passing through key chokepoints such as Hormuz, and the exchange rate of your own currency. Businesses that rely on imports can also check freight and insurance quotes, and consider fixing prices or building a small cash buffer while costs remain unpredictable.
Editorial Note
References
- International Monetary Fund IMF
- Al Jazeera
- The economic impacts of the COVID-19 crisis
- IMF World Economic Outlook, October 2026
- Pakistan Bureau of Statistics

As an economics writer at Tech and Tips Economy, Siraj Buzdar focuses on demystifying economic policies and financial data. His primary goal is to ensure that general economic topics are clear and easy to understand for the everyday reader. By adjusting the depth and length of his articles based on topic complexity, Siraj works tirelessly to bring approachable economic insights directly to his audience.